Who Calibrates Markets? Evidence from Trader Micro-Data
Published October 2026
Abstract
Past academic work has shown prediction markets, and Kalshi markets in particular, are well-calibrated. What is not well understood, however, is why. In this paper, we use evidence from more than 1 billion trades executed from October 2025 to September 2026 on the world’s largest prediction market to suggest that there may exist, in line with the “superforecaster” literature, a small group of identifiably highly skilled traders who meaningfully contribute to price discovery.
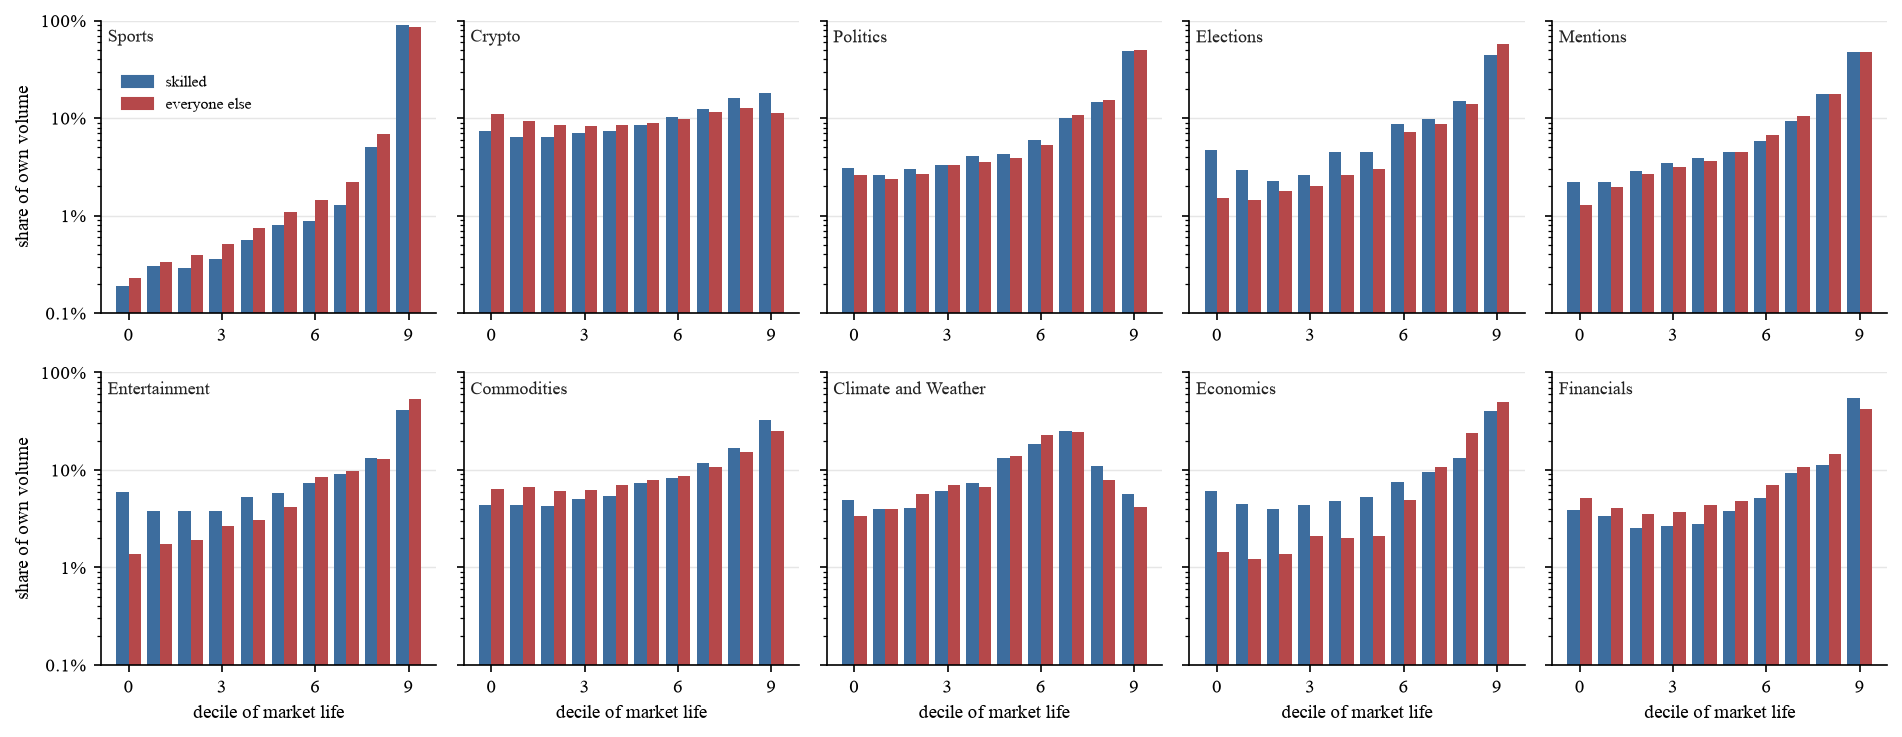
Using a Brier skill score and analysing only takers (excluding market-makers) illustrates that under a strict false discovery threshold, 0.15 percent of traders forecast significantly better than the markets they trade against. This skill persists out of sample and is largely orthogonal to profit. After a skilled taker’s trade, the weighted midpoint moves 1.7 cents toward their direction by the next order and 3.3 cents by close, which constitutes most of the 3.8-cent gap between the pre-trade midpoint and the outcome. A difference-in-differences design against volume-matched markets finds the same, with each additional skilled trader having diminishing returns. Markets with more skilled traders tend to also be more accurate on average.
Overall, prices move toward the outcome after the trades of skilled traders, not necessarily profitable ones. Skilled trading thus joins volume, the total number of traders, and time to resolution as a source of accuracy and calibration in prediction markets.
Keywords: prediction markets, price discovery, forecast skill, Brier score, market microstructure.
JEL Classification: C12, G14, D83.